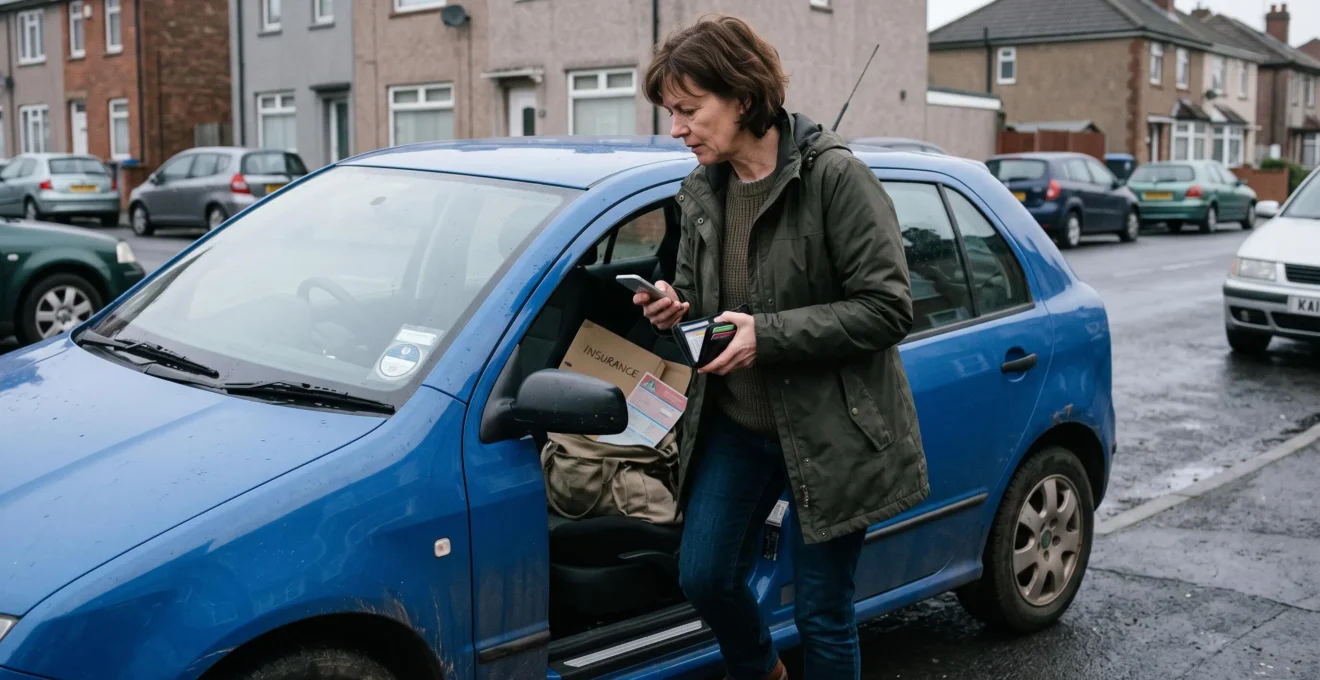
A car can be perfectly legal when purchased or registered but become unlawful to use later. Insurance can expire, vehicle tax can lapse, an MOT certificate can reach its expiry date, or a driver’s circumstances can change. These obligations are not completed once and forgotten: they must remain satisfied whenever the relevant law requires them.
For UK motorists, the central requirements concern a valid driving licence, appropriate motor insurance, vehicle tax where applicable, MOT certification when required, and the vehicle’s continuing roadworthiness. The precise responsibility differs between the driver, registered keeper and vehicle owner.
These distinctions matter particularly when borrowing a car, returning a vehicle to use after several months, driving for work or moving between private property and a public road. An apparently valid insurance policy may not cover a particular driver or journey.
This guide focuses on the rules applying in Great Britain, principally England, Scotland and Wales. Northern Ireland has some separate administrative arrangements, while other English-speaking countries operate under their own road-traffic laws.
Essential driving obligations at a glance
- Legal compliance must continue throughout the period of road use: a valid licence, appropriate insurance, vehicle tax and MOT status cannot simply be assumed from an earlier check.
- Drivers must establish that they are personally entitled and insured to drive, even when the vehicle belongs to a relative, employer or rental company.
- Changes in vehicle use, insurance arrangements, registered status or personal circumstances should trigger a fresh check before the next affected journey.
- Why Can a Driver Become Non-Compliant After Starting a Legal Journey?
- How Can You Check Your Legal Duties Before Driving a Car You Rarely Use?
- Driver Duty or Vehicle Duty: Who Must Ensure Each Requirement Is Met?
- Why Is It Risky to Assume Someone Else Has Checked the Vehicle’s Legal Status?
- When Do New Driving Obligations Arise After a Change in Vehicle Use?
- When Do Road-Legal Requirements Begin During a Journey From Private Land?
- Licence, Insurance, Tax or MOT: Which Requirement Applies to Whom?
- Which Legal Duties Must Drivers Keep Up to Date Before Using a Car?
Why Can a Driver Become Non-Compliant After Starting a Legal Journey?
A driver can become legally non-compliant during a journey because the conditions permitting them to drive are not necessarily fixed at departure. Insurance cover may end, an administrative requirement may reach its expiry date, or the purpose of a journey may change. Whether an immediate legal breach occurs depends on the particular requirement and circumstances.
Consider a hypothetical driver who leaves home while their insurance policy is active. During the journey, the policy’s contractual period ends without renewal. If no replacement cover applies, continuing to drive on a road or in a public place creates an uninsured-driving problem, regardless of how carefully the vehicle is being driven.
Another hypothetical example involves a driver whose insurance permits social and domestic use but who begins carrying passengers for payment. The new activity may fall outside the agreed cover. The legal and contractual consequences depend on the policy wording, the nature of the activity and any applicable statutory protections. It is not correct to assume that every change automatically cancels the entire policy.
This illustrates an important distinction between driving conduct and administrative or insurance compliance. A driver might obey speed limits, traffic lights and road signs while lacking the legal authorisation required for the journey.
The UK government’s legal obligations for drivers and riders identify the core requirements, including licensing, registration, vehicle tax, MOT certification where required, roadworthiness and insurance covering the vehicle’s actual use.
Some obligations operate differently. An MOT certificate is not necessarily invalidated by a mechanical fault discovered during a journey, but the vehicle may nevertheless become unroadworthy. Similarly, the expiry of a licence photocard does not always have exactly the same implications as losing the underlying entitlement to drive; the circumstances must be assessed separately.
For tax or MOT expiry, the relevant date and any applicable exception matter. A missed insurance payment, meanwhile, does not necessarily terminate cover instantly: the insurer’s contractual arrangements and effective cancellation date must be established.
The practical lesson is to resolve known expiry dates and changes in cover before departure, and to stop using the vehicle where a material legal requirement is no longer satisfied.
How Can You Check Your Legal Duties Before Driving a Car You Rarely Use?
Before driving a rarely used car, check four essentials: vehicle tax, insurance covering the intended driver and journey, MOT validity where required, and the driver’s licence entitlement. A car being parked for months does not guarantee that its previous documents remain valid. Its roadworthiness also needs checking before it returns to use.
The most common oversight is assuming that inactivity preserves legal status. A vehicle might have an expired MOT, an insurance policy that was not renewed, or an administrative status that prevents ordinary road use. A separate SORN declaration changes the position for vehicles kept off public roads, but it does not authorise normal driving.
In Great Britain, the registration number can be used with the official DVLA vehicle information service to review recorded vehicle-tax expiry, SORN status and MOT expiry. This is a useful starting point rather than a complete assessment of driving legality.
For insurance, confirm not just whether a policy exists but whether it covers the intended driver and use. A vehicle-insurance database check does not establish every contractual restriction. Review the certificate and schedule, especially if the main driver, commuting arrangements or vehicle use have changed.
Next, verify the licence category and any restrictions attached to the driver. A vehicle may be perfectly compliant while the person intending to drive is not authorised to operate it.
SORN requires particular attention. A vehicle declared off road cannot simply be returned to ordinary public-road use because its owner decides to drive it. The necessary vehicle tax and insurance arrangements must be put in place, together with the other applicable requirements. Specific limited exceptions can apply to journeys for MOT testing, subject to their legal conditions.
Finally, inspect tyres, lights, brakes and other safety-critical features. A current MOT certificate is not a guarantee of present roadworthiness, particularly after an extended period without use.
If any status cannot be confirmed, resolve the uncertainty before driving on a public road. Where the car has been stored for a long period, mechanical inspection may be as important as document verification.
Driver Duty or Vehicle Duty: Who Must Ensure Each Requirement Is Met?
Driving obligations attach to different parties. Licence entitlement and fitness to drive concern the driver; vehicle tax and registration principally involve the registered keeper; and MOT and roadworthiness requirements concern the vehicle and those responsible for its use. Motor insurance must cover the actual driver and journey, regardless of who arranged the policy.
The distinction matters because ownership, registration and permission to drive are not interchangeable. A registered keeper can be different from the legal owner. The person driving may be neither.
Vehicle tax is primarily a registered-keeper responsibility, and it would be misleading to suggest that every driver automatically commits the same tax-administration offence as the keeper. Nevertheless, an untaxed vehicle may be subject to enforcement, and drivers should confirm its lawful status before use.
Insurance creates a more direct personal risk. Permission from the owner does not establish that the borrower has appropriate cover. A policy covering one named driver may exclude someone else, while a driver’s own comprehensive policy does not automatically authorise driving other cars.
Responsibility can also be shared in employment situations. An employer may organise fleet insurance, inspections, servicing and administrative renewals, but employees still need appropriate driving entitlement and must not knowingly use an unsafe vehicle.
A simple way to distribute checks is to consider three questions:
- Does the duty follow the person? Check licence entitlement, eyesight, fitness to drive and any relevant restrictions.
- Does it follow the vehicle? Confirm registration, tax status, MOT requirements and present roadworthiness.
- Does it depend on actual use? Establish that insurance covers the driver, journey purpose and relevant operating conditions.
These categories overlap. A company may arrange insurance at fleet level while the individual driver’s entitlement and permitted activities determine whether a particular journey is covered.
For hired vehicles, the rental agreement, insurance arrangements and permitted-driver conditions also matter. The fact that a rental business has handed over the keys does not eliminate every responsibility of the person driving.
Shared responsibility works best when there is a clear confirmation process, not an assumption that one party’s involvement removes the obligations of everyone else.
Why Is It Risky to Assume Someone Else Has Checked the Vehicle’s Legal Status?
Assuming that another person has checked a vehicle can leave important requirements unverified. The owner may believe the borrower has their own insurance, while the borrower assumes the owner’s policy covers everyone. Even good-faith misunderstandings may expose a driver to uninsured-driving penalties and potentially serious financial consequences.
Shared vehicles create opportunities for this kind of uncertainty. Families, colleagues and friends may all use the same car without reviewing the policy after a renewal or change of circumstances.
Consider a hypothetical family arrangement. A parent gives an adult child permission to use a car for a weekend. The vehicle is insured, but the child is not a named driver and does not hold separate cover permitting that use. Permission to borrow the car does not itself provide insurance.
UK government guidance on driving without insurance confirms that a driver can be penalised even when the vehicle itself has insurance. The published fixed penalty is £300 and six penalty points; court proceedings can lead to an unlimited fine or disqualification. Police also have powers to seize uninsured vehicles.
The distinction between personal reassurance and documented confirmation is therefore essential. Being told that everything is up to date is not equivalent to confirming the policy’s authorised drivers, permitted uses and relevant limitations.
Before borrowing a vehicle, ask to see the appropriate insurance evidence, establish that the intended use is covered, and confirm its tax and MOT status where relevant. If a contractual condition remains unclear, seek confirmation from the insurer before driving.
Insurance disputes after accidents can be complex. A policy restriction may affect the driver’s contractual protection without necessarily extinguishing every statutory protection for injured third parties. Whether an insurer can recover sums from another party depends on the applicable legal and contractual circumstances.
Being a named driver is not unlimited permission either. Named-driver cover operates within the policy’s terms, including any restrictions on vehicle use, territory and other conditions.
A few minutes spent reviewing the relevant information can prevent uncertainty from becoming a legal dispute after an incident.
When Do New Driving Obligations Arise After a Change in Vehicle Use?
New driving obligations can arise when a vehicle is used differently, its main driver changes, the keeper moves home, or modifications alter the vehicle’s characteristics. These changes may affect insurance terms, DVLA records, driving entitlement or inspection requirements. The need to notify an insurer depends on the policy conditions and the applicable legal rules.
Switching from private journeys to business travel is a common example. Insurance arranged for social and domestic use may not cover business activities. Commuting and business use are also different classifications under many policies, so the intended journey must match the cover provided.
Changes in the principal driver can be equally important. A vehicle previously used mainly by one family member might later be driven predominantly by someone else. This should prompt a review of the policy and the information supplied to the insurer.
Moving home can require administrative updates to driving-licence and vehicle-registration records. It may also affect insurance pricing or conditions. Vehicle modifications, including certain adaptations or towing arrangements, can create additional questions about insurance, technical compliance and licence entitlement.
However, a distinction is necessary between inaccurate information supplied when arranging insurance and a change arising after a policy has already started.
The Financial Ombudsman Service guidance on insurance misrepresentation and non-disclosure explains that post-inception notification duties may depend on the policy terms. A failure to report a later change is not automatically a misrepresentation under the Consumer Insurance (Disclosure and Representations) Act 2012.
Where the applicable requirements are satisfied, insurers may have remedies concerning premiums, policy terms or claims. Those remedies are not automatic consequences of every unreported change.
A practical compliance review after a significant change should therefore revisit:
- Insurance: does the cover still match the driver, address, activity and vehicle?
- Vehicle tax: has anything changed about the vehicle’s taxable status or registration?
- MOT: does its classification or inspection requirement change?
- Licence: does the driver still hold the necessary entitlement for the vehicle and any trailer?
Moving between UK jurisdictions or relocating abroad requires particular care. Northern Ireland has separate arrangements for some vehicle and licensing services, while another country may impose different registration, testing and insurance requirements. No universal transfer deadline should be assumed.
The safest sequence is to identify the change, check the relevant documents, obtain any necessary confirmation, and only then use the vehicle for the new purpose.
When Do Road-Legal Requirements Begin During a Journey From Private Land?
Road-legal requirements can apply before a vehicle reaches an ordinary public highway. In Great Britain, compulsory third-party motor insurance applies to driving on roads and in public places. A privately owned car park may qualify as a public place, depending on access and circumstances. Other obligations have their own statutory scope and exceptions.
The legal distinction is not simply between public ownership and private ownership. A supermarket car park, for example, may be privately owned while remaining accessible to members of the public. Driving there can therefore engage road-traffic insurance requirements.
By contrast, a secured private compound with access restricted to authorised individuals presents a different factual situation. Whether particular road-traffic provisions apply depends on the legislation involved, the location and how access operates.
A useful practical question is: Can members of the public ordinarily enter this area without individual permission? If so, drivers should not assume that the space falls outside compulsory motor-insurance rules.
This is a precautionary test, not a conclusive legal definition. Access by the public is a significant consideration, but the classification of a location ultimately depends on its circumstances and the applicable law.
The position also differs between legal requirements. Compulsory motor insurance expressly addresses roads and public places, whereas vehicle-tax and MOT legislation operate through their own rules, including provisions relating to roads and particular exemptions. It would be inaccurate to treat every publicly accessible private space as triggering every requirement identically.
For a vehicle leaving a genuinely private driveway, the owner should establish its road-legal status before entering the public road. The distance travelled is not a general exemption from ordinary driving requirements.
Special arrangements can exist for certain journeys to or from MOT testing, but drivers must satisfy the conditions of the relevant exception. Such provisions do not give blanket permission to drive an uninsured vehicle.
If the public-access status of a location is uncertain, arranging appropriate insurance and confirming the vehicle’s legal status before moving it is the prudent course.
Licence, Insurance, Tax or MOT: Which Requirement Applies to Whom?
Licence, insurance, vehicle tax and MOT obligations apply through different legal mechanisms. A licence authorises a person to drive specified vehicle categories; insurance must cover the person’s actual use; vehicle tax concerns the vehicle and its registration status; and MOT testing concerns vehicles that fall within testing requirements. None automatically proves compliance with the others.
Understanding these differences prevents a common mistake: treating an apparently valid registration or insurance record as confirmation that a particular journey is lawful.
| Requirement | Primary responsibility or subject | What to verify |
|---|---|---|
| Driving licence | Individual driver | Entitlement for the relevant vehicle category, validity and applicable restrictions. |
| Motor insurance | Actual driver and insured vehicle use | Policy in force, authorised driver, vehicle, permitted journey purpose and relevant conditions. |
| Vehicle tax | Vehicle and registered keeper | Valid tax status or an applicable exemption, including any relevant SORN status. |
| MOT | Vehicle and those responsible for its lawful use | Whether testing is required, whether the certificate is current and whether the vehicle remains roadworthy. |
The four requirements also begin and renew at different times. Driving entitlement depends on the licence and its conditions. Insurance depends on the policy period and cover. Vehicle-tax obligations follow the statutory system, while MOT testing depends on factors such as age, type and jurisdiction.
For ordinary cars in Great Britain, an initial MOT is generally required when the vehicle reaches three years of age, followed by annual testing. Different requirements or exemptions can apply to certain vehicles, and Northern Ireland operates separate testing arrangements.
Some historic vehicles are exempt from MOT testing, while other vehicles may have tax exemptions. An exemption from one requirement does not automatically remove the others. Even an MOT-exempt vehicle must remain roadworthy when used.
Different ownership and usage situations therefore produce different checks:
| Situation | Driver’s immediate checks | Additional consideration |
|---|---|---|
| Driving your own car | Licence, insurance, tax, MOT where required and roadworthiness. | Keep registered details and relevant policy information accurate. |
| Borrowing another person’s car | Personal insurance entitlement, licence and vehicle compliance. | Owner’s permission does not establish appropriate insurance. |
| Keeping a car off public roads | No ordinary driving check while it remains unused, but requirements must be reassessed before use. | Check SORN eligibility, off-road arrangements and continuous-insurance rules. |
The underlying principle is that a vehicle’s administrative record, a driver’s entitlement and an insurance contract answer different legal questions. All relevant answers must be satisfactory for the intended journey.
Once the responsibilities are understood, they can be converted into a short routine that prevents overlooked renewals and reduces uncertainty before travel.
Key takeaways before your next drive
- Identify the actual driver and intended journey before relying on any motor-insurance policy.
- Distinguish the registered keeper’s administrative obligations from the driver’s personal legal entitlement.
- Use recorded expiry dates and confirmed changes in circumstances to trigger timely reviews rather than depending on memory.
Which Legal Duties Must Drivers Keep Up to Date Before Using a Car?
Before using a car in Great Britain, drivers must maintain the appropriate driving entitlement, insurance covering their actual use, lawful vehicle-tax status, MOT certification where required and a roadworthy vehicle. They must also remain fit to drive and comply with relevant licence conditions. Each requirement needs attention throughout its applicable period, not just when the car is first obtained.
Legal compliance is best treated as an ongoing maintenance responsibility. Insurance policies have renewal dates and contractual terms; MOT certificates expire; driving licences and their associated entitlements may require renewal or review; and vehicle-tax status can change.
Some systems offer reminders or automatic renewals, but these are not substitutes for confirming that an obligation has actually been satisfied. A failed payment, unprocessed renewal or altered circumstance can create an unexpected gap.
Physical roadworthiness also matters. Drivers should consider tyres, lighting, braking performance, visibility and any known mechanical defects. Holding an MOT certificate does not authorise the continued use of a dangerously defective vehicle.
A five-step pre-driving compliance checklist
- Confirm your driving entitlement. Check the relevant licence category, any restrictions and expiry information; retain a note of the verified status.
- Verify insurance for the actual journey. Review the policy period, insured drivers and permitted uses; identify the current policy evidence or insurer confirmation.
- Check vehicle-tax status. Confirm the current record and any applicable exemption or SORN position; record the result and relevant renewal date.
- Confirm MOT requirements and roadworthiness. Check the testing record or applicable exemption, then inspect obvious safety-critical features; note any defect requiring attention.
- Set up a single renewal and change-review record. Collect the relevant dates, reminders and outstanding confirmations, and update it when the vehicle, policy or driver’s circumstances change.
The resulting record should distinguish official status information from personal notes. A screenshot or saved reminder can help organise checks, but it does not itself create valid insurance, driving entitlement or vehicle-tax status.
Drivers should also know which documents may be requested by police. In Great Britain, a driver may be required to produce their driving licence, insurance certificate and applicable MOT certificate. Where permitted, documents not produced immediately may need to be presented at a police station within seven days. That provision does not authorise driving without the underlying legal requirements being met.
If a policy, tax record, testing requirement or licence entitlement cannot be confirmed, do not assume that an earlier document remains sufficient. Resolve the uncertainty through the relevant authority or provider before using the vehicle.
Choose one vehicle you expect to use next, confirm its current legal status and place the relevant renewal dates in a calendar. Repeat the review whenever your insurance, vehicle, intended use or personal driving circumstances change.
Can I drive a car if the owner has insurance but I am not named on the policy?
Only if appropriate insurance independently covers your use of that vehicle. This might be through a policy that permits you to drive it or another valid insurance arrangement. The owner’s insurance does not automatically cover every borrower, and permission to drive is not a substitute for insurance.
Does a valid MOT certificate mean the car is legally safe to drive?
No. An MOT certificate records the outcome of a test at a particular time. A vehicle can develop dangerous defects afterwards, and its continuing roadworthiness remains a separate legal requirement. Safety-critical faults must not be ignored simply because the MOT has not expired.
Can I leave an unused car uninsured if it is parked on private property?
In Great Britain, a vehicle normally needs to be insured unless an applicable exception is satisfied, such as a valid SORN for a vehicle kept off public roads. Merely parking a registered vehicle on a driveway does not automatically remove continuous-insurance obligations. Check its tax and SORN status before making changes.
Must I notify my motor insurer every time my driving habits change?
Not necessarily. Notification duties depend on the change and the insurance contract. Significant changes such as a new principal driver, different business use or a change of address should prompt a review of the policy terms. Ask the insurer when the notification requirement is unclear, rather than assuming every variation immediately cancels cover.
Do the same licence, tax and MOT rules apply throughout the United Kingdom?
Not in every administrative detail. Great Britain and Northern Ireland share many underlying road-safety principles, but some licensing, vehicle-registration and testing arrangements differ. Drivers should use the official service appropriate to the jurisdiction in which the vehicle is registered and operated.