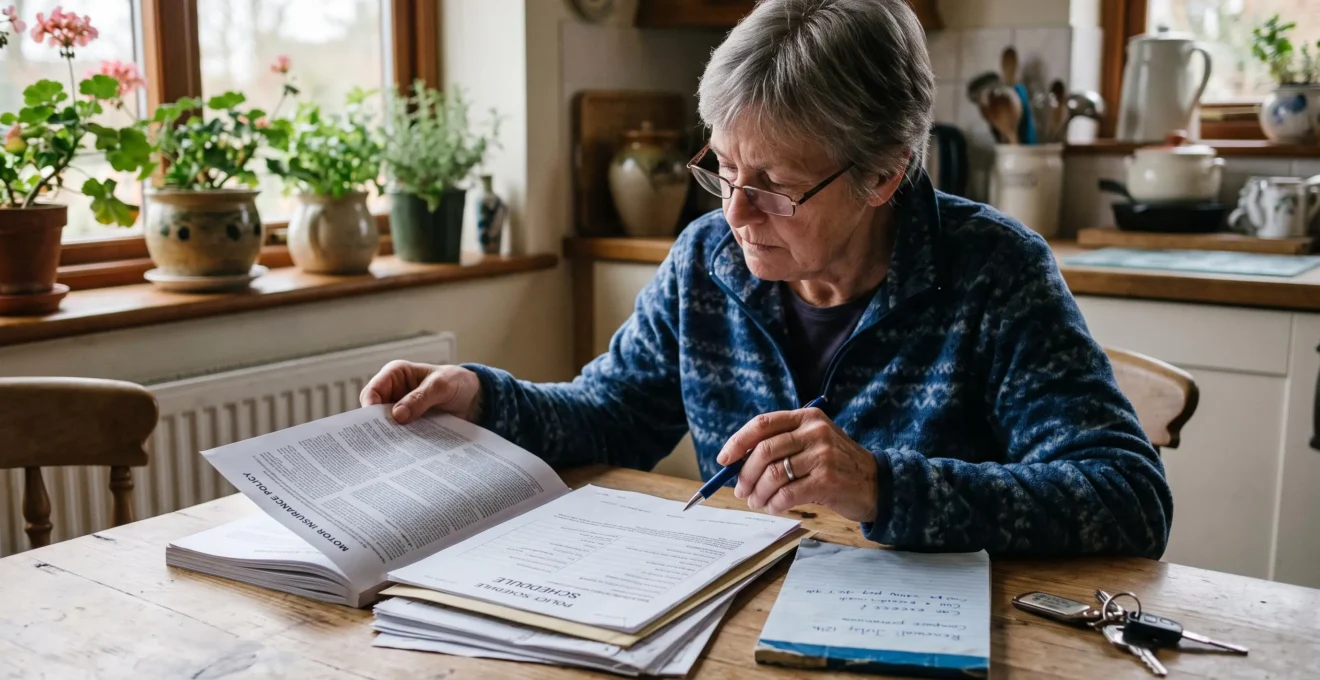
A motor insurance policy is rarely contained in a single document. The paperwork typically combines standard policy wording, a personalised schedule, a certificate of insurance and, sometimes, endorsements that modify particular terms. Each document answers a different question, and reading only one can produce a misleading picture of your protection.
Start with the schedule to identify the vehicle, insured drivers, permitted use, selected cover and excesses. Then consult the wording for definitions, exclusions, conditions and claims procedures. Finally, check every endorsement for changes to those arrangements. Where a document refers to another clause, follow that reference before deciding what is covered.
The precise contractual hierarchy and legal consequences depend on the policy and applicable jurisdiction. This guide explains a practical reading method for English-speaking drivers, with UK regulatory and industry sources used where relevant. UK documentation requirements and legal rules should not be assumed to apply automatically in other countries.
Motor insurance documents: the essentials
- The schedule personalises your insurance; the wording explains the standard terms; endorsements may modify either.
- Check authorised drivers, permitted vehicle use, exclusions, excesses and claims obligations before relying on cover.
- Review documents whenever the insured risk changes, at renewal and immediately after an incident.
- Why Can Your Policy Schedule Differ From the Main Insurance Wording?
- How Can You Read a Motor Policy Without Getting Lost in the Small Print?
- Schedule, Certificate or Policy Wording: Which Document Tells You What?
- Which Policy Clauses Can Restrict Cover When Drivers Least Expect It?
- When Should You Recheck Your Motor Policy Documents During the Policy Year?
- How Can You Check an Insurance Endorsement Before Accepting a Motor Policy?
- When Is Responsibility Assessed During a Motor Insurance Claim?
- When Does a Motor Insurance Endorsement Change What Your Policy Covers?
Why Can Your Policy Schedule Differ From the Main Insurance Wording?
Your motor insurance schedule can differ from the main wording because the two documents perform different functions. The wording describes standard contractual provisions, while the schedule records the terms selected or agreed for your particular risk. An endorsement may add further changes. The documents must be read together, and their contractual priority should be checked rather than assumed.
Think of the wording as the underlying contract framework. It defines available cover, exclusions, claims processes and general conditions. The schedule identifies how that framework applies to the insured vehicle and policyholder, including which sections are operative and what excesses or restrictions apply.
Insurers assess information such as the vehicle, its drivers and its intended use when deciding what terms to offer. Those underwriting decisions may appear in the schedule or in endorsements referenced by it.
For example, a hypothetical policy wording might describe business-use protection as an available category, while the schedule specifies social, domestic and pleasure use only. The availability of business cover in the standard documentation would not mean it had been purchased.
Do not assume the schedule automatically overrides every conflicting provision. A policy may contain an express order-of-precedence clause, or an endorsement may expressly amend a particular provision. The applicable legal rules also matter. Where terms appear inconsistent, request clarification from the insurer rather than selecting whichever version seems more favourable.
A useful comparison focuses on the differences most likely to affect a claim.
| Item to inspect | Standard wording | Personal schedule or endorsement |
|---|---|---|
| Excesses | Explains how excesses operate | Identifies applicable amounts and variations |
| Drivers | Defines driver eligibility and restrictions | Identifies permitted drivers or driver categories |
| Vehicle use | Explains available use categories | Records the agreed use category |
| Territory | Sets geographic conditions | May specify individual extensions or restrictions |
| Optional benefits | Describes benefits and eligibility | Indicates which benefits were selected |
| Endorsements | Contains provisions that may be amended | Identifies additional contractual changes |
Pay particular attention to changes from an earlier schedule. An endorsement introduced during a previous policy year might continue at renewal. A current schedule referencing an unfamiliar endorsement number is a reason to investigate, not proof that the restriction has disappeared.
The Financial Ombudsman Service analysis of insurance misrepresentation and non-disclosure explains why inaccurate or incomplete information can matter to insurance terms. In the UK consumer context, the consequences depend on the circumstances and applicable law; a mistaken answer does not automatically invalidate every policy.
The result should be a clear statement of the cover actually agreed, not merely a description of what the insurer’s standard product can provide.
How Can You Read a Motor Policy Without Getting Lost in the Small Print?
The simplest way to read a motor policy is to follow a fixed order: schedule, definitions, general exclusions, contractual conditions and claims procedure. This reveals what protection was selected, how important terms are interpreted and what obligations apply. Rather than reading every page sequentially, trace each relevant provision across the complete policy pack.
Begin with the schedule and mark the principal cover sections, policy period, permitted use, insured vehicle, drivers and excesses. Next, read the definitions. Ordinary-looking words such as “loss”, “modification” or “authorised driver” may have precise contractual meanings that differ from everyday usage.
Then locate exclusions applying to the entire policy, followed by exclusions within individual sections. A general exclusion may be qualified by a specific extension, exception or endorsement. Reading only the first exclusion list can therefore produce an incomplete answer.
Finally, examine the conditions and claims procedure. These provisions explain what must happen when circumstances change or an incident occurs, including notification, cooperation, evidence and repair arrangements.
Pay attention to operative wording:
- “Must” or “shall” generally signals a stated obligation, although its legal effect depends on context.
- “May” often describes an available action or contractual discretion, rather than an unconditional requirement.
- “Subject to” indicates that one provision depends on another.
- “Unless”, “except” and “provided that” can substantially change the scope of a restriction.
Conditions described as “conditions precedent” deserve close attention. Depending on their wording and applicable law, failure to satisfy such a condition can affect entitlement to cover. However, the label alone does not establish that every breach automatically defeats an entire claim. The condition, its relevance to the loss and applicable legal protections must be considered.
Build a one-page reference sheet containing the applicable limits, excesses, endorsements, major exclusions, notification requirements and claims contact details. Include page or clause references beside each entry so the original wording remains easy to locate.
Create your five-part policy reference sheet
- Record the policy number, period, covered vehicle and authorised drivers. Deliverable: a verified identification section.
- List the selected cover sections, main limits and applicable excesses. Deliverable: a coverage summary with clause references.
- Identify whole-policy exclusions and any specific exceptions. Deliverable: a referenced exclusions list.
- Record endorsement numbers, effective dates and their practical effects. Deliverable: a current endorsements register.
- Extract notification requirements, claims contacts and relevant deadlines. Deliverable: a concise incident-response reference.
The reference sheet is a navigation aid, not a replacement contract. When a claim depends on exact wording, the full operative documents must still be consulted.
Schedule, Certificate or Policy Wording: Which Document Tells You What?
The insurance certificate, policy schedule and policy wording answer different questions. The certificate provides prescribed evidence of insurance where that document is used by law. The schedule records personalised insurance details, while the wording explains contractual rights, restrictions and procedures. None should be treated as a complete substitute for the others when determining whether a particular loss is covered.
The distinction is particularly important because documentation systems vary between English-speaking countries. A requirement that applies to a UK driver may not apply in the same form in Australia, Canada, New Zealand or the United States.
| Document | Main purpose | What it does not establish alone |
|---|---|---|
| Insurance certificate | Evidence of insurance in the form required by the relevant system | Every optional benefit or every contractual qualification |
| Policy schedule | Personalised cover, insured details and selected terms | All definitions, exclusions and claims conditions |
| Policy wording | Full standard contractual provisions | Which optional sections or individual variations apply |
| Endorsement | Modification or clarification of specified terms | The complete contract without the provisions it affects |
For UK drivers, GOV.UK guidance on drivers’ legal obligations confirms the need for at least third-party insurance covering the driver’s use of the vehicle and explains the insurance documents police may request.
That does not mean a certificate establishes every aspect of contractual coverage. A policyholder checking windscreen protection, breakdown assistance or a particular excess should normally consult the schedule and relevant wording, including applicable endorsements.
Suppose a driver receives a revised certificate after changing vehicles. The new document may evidence the updated insurance arrangement, but it should be checked alongside the revised schedule to confirm the vehicle details, cover period, permitted drivers and any altered conditions.
Keep older documents when changes occur. They may help establish what terms applied before a mid-term amendment. The most recently issued document is not necessarily decisive for an earlier incident: the relevant effective dates, agreed amendments and contractual rules determine which terms apply.
The UK Financial Ombudsman Service identifies schedules, certificates and policy terms among the documents it may examine in motor insurance complaints. This illustrates why a dispute often requires the complete documentary record rather than a single certificate.
Once those roles are understood, the next priority is identifying contractual restrictions that can change the outcome of an otherwise ordinary claim.
Which Policy Clauses Can Restrict Cover When Drivers Least Expect It?
Motor insurance cover can be restricted by clauses governing who drives, how a vehicle is used, its condition, modifications and where it is driven. Other restrictions concern excesses, compensation limits and compliance with policy obligations. The practical danger is assuming that an insured vehicle is protected in every situation simply because the policy remains active.
Driver eligibility is a frequent source of misunderstanding. A policy may insure named drivers only, set conditions for additional drivers or limit any driving-other-cars benefit. Being legally licensed does not, by itself, establish entitlement under a particular policy.
Vehicle use is equally important. Social, domestic and pleasure driving may be treated differently from commuting, business journeys or commercial activities. The exact categories and permitted activities depend on the insurer’s wording.
The Association of British Insurers‘ motor insurance information identifies unauthorised drivers, unpermitted business use and unroadworthy vehicles among common coverage concerns. It also explains why comprehensive insurance should not be assumed to include every optional benefit.
Consider three hypothetical situations:
- A driver uses a car for business journeys despite a schedule limited to personal use. The insurer may question whether the journey falls within the agreed use category.
- A vehicle modification is not reflected in information supplied to the insurer. A subsequent claim may raise questions about disclosure, eligibility or the effect of specific contractual terms.
- A driver takes the vehicle into a territory outside the policy’s stated geographic scope. Protection may be limited or require an extension, depending on the documents.
These examples illustrate possible coverage disputes, not automatic grounds for rejecting claims. The outcome depends on the terms, the facts and applicable law.
Conditions concerning vehicle security, roadworthiness, notifications or cooperation can also be significant. A condition precedent may have more serious consequences than an ordinary administrative obligation, but its enforceability and the remedy for breach must not be inferred solely from its heading.
Financial limitations can be less obvious. An excess may make a small own-damage claim uneconomic, while indemnity limits may differ depending on whether they apply per item, person, event or policy period.
Finally, distinguish contractual protection for the policyholder’s own loss from compulsory third-party liability requirements. In some jurisdictions, an insurer may remain subject to statutory obligations towards third parties even where a policy condition affects its position towards the insured person.
Test your documents against three questions: Who is permitted to drive? Which uses and territories are permitted? Which exclusions or conditions could restrict a claim? If any answer remains unclear, ask the insurer or broker for written clarification referencing the relevant clause.
Because these details can change during a policy year, checking them only at the original purchase is insufficient.
When Should You Recheck Your Motor Policy Documents During the Policy Year?
Recheck motor insurance documents at renewal, after a relevant change in circumstances, whenever a revised schedule or endorsement arrives, and after an incident. These events can alter either the insured risk or the terms governing a claim. The purpose is to confirm the operative cover at each relevant date, not simply to repeat an annual paperwork exercise.
Renewal is an important review point because cover levels, excesses, optional benefits or restrictions may change. Compare the proposed renewal schedule with the existing one and examine any accompanying notices or revised wording.
A focused renewal review should identify:
- Changes to drivers, vehicles, permitted use or territory.
- Altered excesses, limits and optional benefits.
- New, withdrawn or continuing endorsements.
- Changes to exclusions, conditions or claims arrangements.
- Personal information that needs correction or confirmation.
During the year, events such as changing the vehicle, adding a driver, moving address or altering how the car is used may trigger notification requirements. Check the policy’s own provision on changes of circumstances and any questions or instructions supplied by the insurer.
Do not assume every change must be notified under the same deadline or that failure to notify always voids the policy. Contractual obligations and legal remedies vary. In the UK, the Financial Ombudsman Service’s discussion of misrepresentation distinguishes different circumstances and potential consequences, including situations where incorrect information is provided or reconfirmed at renewal.
Also distinguish reporting details to a vehicle registration or licensing authority from notifying the insurer. Completing one obligation does not necessarily satisfy the other.
After an accident, locate the claims conditions immediately. Check how and when the incident must be reported, what supporting evidence is needed, whether repairs require approval and what the wording says about admissions or settlements.
Preserve the version of the policy documents that applied at the incident date. Subsequent amendments should be stored separately so that the insurer can identify the correct contractual position without ambiguity.
The same approach becomes especially important when a new endorsement changes a specific term without replacing the entire policy document.
How Can You Check an Insurance Endorsement Before Accepting a Motor Policy?
Before accepting a motor insurance endorsement, identify the provision it changes, read the original wording and determine the combined effect on your cover. Check the endorsement’s number, title, conditions and effective date. If the practical outcome is unclear, request written confirmation before agreeing to the amended terms or relying on the protection described.
An endorsement is not automatically an additional benefit. It may extend cover, restrict an existing entitlement, impose a requirement or clarify how a provision operates.
For example, an insurer might offer cover subject to a vehicle security condition. Alternatively, a policyholder might request an amendment adding another driver. These changes involve different practical risks, but either may affect more than one provision.
Begin by locating the endorsement identifier in the schedule and finding the complete corresponding text. Then identify the precise clause being modified. Words such as “replaced”, “deleted”, “extended” or “subject to” may show how the original provision has changed.
Next, examine the interaction with existing definitions, exclusions and limits. A change allowing an additional driver could also introduce a different excess. A vehicle-use extension might operate only within a defined territory or subject to additional conditions.
Hypothetical example: a security endorsement
An insurer offers comprehensive cover for a particular vehicle subject to a stated security-device requirement. The schedule identifies the endorsement, but the headline product description remains unchanged.
The policyholder should establish exactly what device is required, when the requirement applies, whether proof is needed and what the contract says about non-compliance. Without that information, the practical scope of theft protection remains uncertain.
Where an endorsement is imposed as a condition of offering insurance, consider asking whether the restriction can be amended or removed. Alternative quotations may help establish whether another policy better matches the vehicle’s intended use or the policyholder’s circumstances.
Acceptance formalities also deserve attention. Not every amendment requires a physical signature, and the absence of one does not automatically make an endorsement ineffective. The relevant rules may concern agreement, notice, policy terms or other applicable requirements.
Request a corrected schedule or written explanation if a proposed amendment differs from the agreed quotation. Retain the communication and any final version provided.
Once the endorsement is understood, retain its effective date and contractual wording. Both may become important if a later claim concerns a period close to the amendment.
When Is Responsibility Assessed During a Motor Insurance Claim?
Responsibility is assessed throughout the motor insurance claims process, beginning with the initial account of the incident and continuing through evidence collection, investigation and any liability decision. The insurer may reconsider its position as further information emerges. Importantly, legal responsibility for an accident is not necessarily the same as an insurer’s classification of a claim.
At first notification, the insurer typically records the circumstances reported by the policyholder. This initial record can influence what investigators examine, although it is not necessarily the final account of events.
The investigation may involve statements from drivers and witnesses, photographs, vehicle damage assessments, correspondence or available video evidence. The insurer then considers responsibility and its contractual position in light of the information obtained.
According to the Financial Ombudsman Service guidance on fault claims and no-claims bonuses, an insurer’s decision to accept liability does not necessarily establish that its policyholder personally caused the accident. Insurance claims classifications can reflect how a claim was resolved or whether costs were recovered.
Similarly, being considered not at fault does not remove the policyholder’s contractual duties. Notification, cooperation and evidence requirements can remain relevant even when another driver appears responsible.
After making the scene safe and meeting any emergency or legal reporting obligations, preserve relevant evidence where it is safe to do so. This may include photographs of damage and road conditions, witness contact information, an incident timeline and copies of communications with the insurer.
Provide factual descriptions and distinguish direct observations from assumptions. Avoid making unsupported statements about fault. Where the policy restricts admissions or settlements, read that provision carefully while recognising that contractual wording does not remove legal obligations to provide accurate information.
If an initial statement in the claims file is inaccurate, send a clear written correction identifying the error and the supporting evidence. Retain a copy and request confirmation that the correction has been added to the file.
A claim’s effect on future premiums is a separate question from legal liability. A reported incident may influence renewal pricing even without a claim payment, while the treatment of a no-claims bonus depends on the policy and circumstances.
If the insurer’s liability assessment remains disputed, request its reasoning and supporting evidence. Follow the insurer’s complaints process and, where eligible, the relevant independent dispute-resolution route. In the UK, this may involve the Financial Ombudsman Service.
A reliable claims file also depends on the policy terms that were active when the incident occurred, especially where endorsements changed the cover during the year.
Key takeaways before checking an endorsement
- Confirm an endorsement’s effective date rather than assuming it applied throughout the policy year.
- Read amendments alongside the clauses, definitions and exclusions they affect.
- Request a consolidated record of current terms when multiple amendments have accumulated.
When Does a Motor Insurance Endorsement Change What Your Policy Covers?
A motor insurance endorsement changes cover when it takes effect under the applicable contractual arrangement. That may be at policy inception, renewal or an agreed mid-term date. Its effect depends on the wording, any conditions attached and the policy provisions it modifies. The incident date and the endorsement’s effective date are therefore essential when assessing a claim.
Endorsements can have consequences beyond the immediate change they describe. Adding a driver, replacing a vehicle or extending permitted use may also affect excesses, eligibility, territorial conditions or specific obligations.
Consider the following hypothetical examples.
| Endorsement | Direct change | Other terms to check |
|---|---|---|
| Additional driver | Changes driver eligibility | Driver-specific excesses and restrictions |
| Replacement vehicle | Changes the insured vehicle | Cover value, equipment, modifications and security |
| Business-use extension | Changes permitted journeys | Use definitions, exclusions and territory |
| Security condition | Introduces or changes an obligation | Relevant cover sections, compliance and evidence |
These are possible interactions, not changes that occur automatically in every policy. The schedule and endorsement must establish which adjustments were actually agreed.
Timing can be decisive. Suppose a driver requests business-use cover and receives an endorsement effective from a specified future date. An incident occurring before that date cannot safely be assessed as though the extension had already started. The original policy and any applicable legal provisions must be considered.
Likewise, a condition requiring the policyholder to take a particular action should be distinguished from an amendment that operates without any further step. A security endorsement may require installation or continued operation of equipment, while a change to an excess may simply apply according to its effective terms.
Non-compliance does not have one universal consequence. The insurer’s rights depend on the specific condition, the circumstances of the breach and applicable legal protections. Where an obligation is unclear, ask the insurer to identify both the required action and the contractual consequences of failing to perform it.
Multiple endorsements also create a record-management problem. A restriction introduced several renewals earlier might remain active even though the policyholder no longer remembers its origin. Conversely, a later amendment might expressly replace a previous endorsement.
At renewal, request a consolidated current schedule and complete copies of all endorsements that remain operative. Compare their numbers, descriptions and effective dates against the previous policy pack, and ask for written confirmation of any apparent duplication or conflict.
Before relying on your policy for a journey or reporting a changed risk, verify the current documents, resolve any unclear restriction with your insurer or broker and retain the written answer alongside your policy records.
Can I rely on an insurance quotation instead of the issued policy?
A quotation describes proposed insurance terms and may be subject to assumptions, acceptance or further information. Once insurance is arranged, check the documents actually issued and the terms agreed. If the schedule differs from the quotation, ask the insurer or broker to explain and correct any error.
What should I do if a policy document is missing?
Contact the insurer or broker and request the missing document, identifying the policy number and relevant period. If an endorsement is referenced but not supplied, request its full text. Do not assume that an unexplained restriction is inapplicable simply because its wording is absent from your copy.
Does comprehensive motor insurance cover every kind of damage?
No. Comprehensive cover remains subject to the applicable wording, exclusions, excesses and conditions. Benefits such as breakdown assistance, windscreen protection or a courtesy car can depend on the particular policy. Verify the selected cover in the schedule and the conditions in the wording.
Can I keep my motor insurance documents electronically?
Electronic storage is useful for preserving schedules, wordings, endorsements and correspondence, but legal acceptance of digital evidence of insurance varies by jurisdiction. Check the documentation requirements where you drive and retain accessible copies of the operative documents, including relevant older versions.
Who can clarify a policy clause before I make a claim?
The insurer or authorised broker is the appropriate first contact for clarifying the terms offered or issued. Provide the clause number and a concrete question about the proposed driver, vehicle use or situation. Request a written response and keep it with the policy. For an unresolved dispute, applicable complaints or independent dispute-resolution procedures may be available.