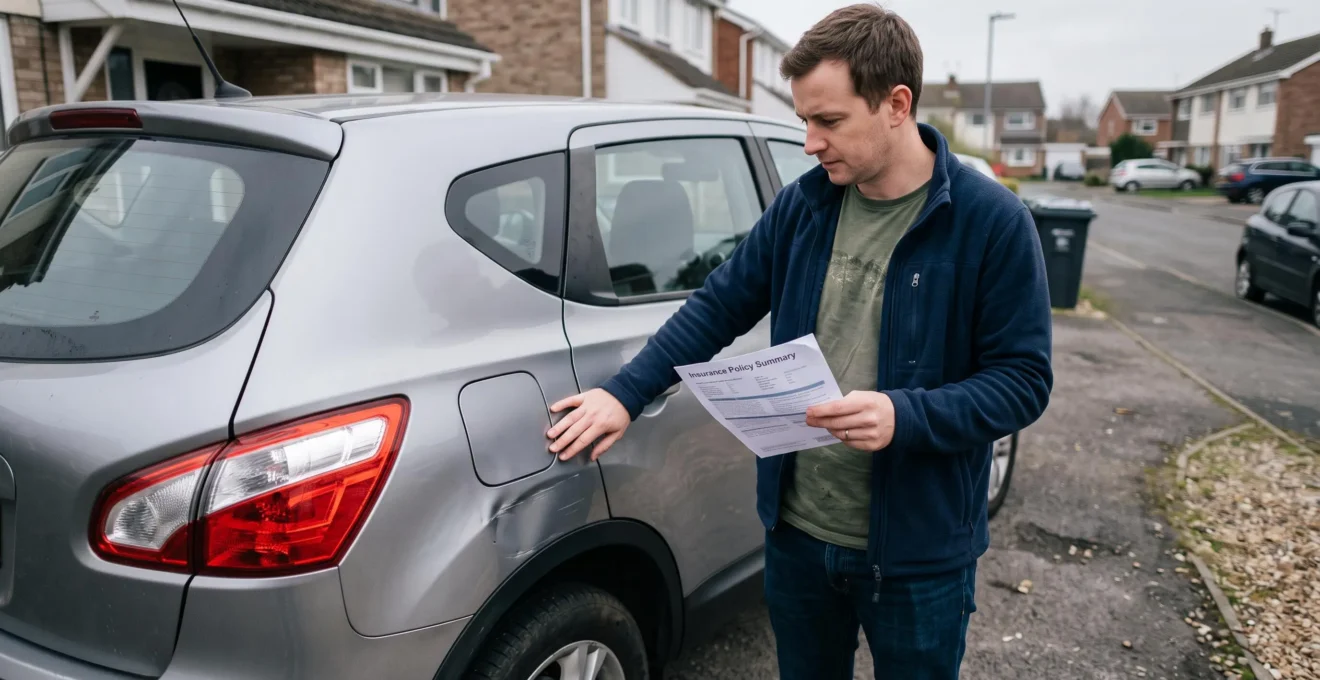
A motor insurance policy can look affordable until an accident leaves you facing a repair bill and a substantial excess. That excess is the part of an eligible insurance claim you must bear yourself, whether through a deduction from the settlement or a payment towards repairs.
Choosing a higher voluntary excess may reduce your premium. But the saving only makes financial sense if you can cover the additional claim cost without borrowing, missing essential payments or exhausting the savings you need for other emergencies.
The practical approach is to compare the full compulsory and voluntary excess, measure it against accessible savings, and calculate how much premium you genuinely save by accepting more risk. The cheapest quote is not necessarily the cheapest policy when something goes wrong.
The examples below use pounds sterling and terminology commonly found in UK motor insurance. Drivers elsewhere should check local policy definitions, excess arrangements and liability rules before applying the same calculations.
Motor insurance excess: the essential decisions
- Calculate your total excess: add the compulsory excess to your chosen voluntary excess, including any applicable claim-specific charges.
- Protect your cash reserves: select an amount you can access promptly without relying on credit or money reserved for essential expenses.
- Compare the real saving: measure the annual premium reduction against the extra amount you might have to pay after a claim.
- Why Does Increasing Your Insurance Excess Often Reduce the Premium?
- How Can You Set an Excess That Your Emergency Fund Can Actually Cover?
- Compulsory or Voluntary Excess: Which One Determines What You Pay?
- How Can a Cheap Policy Become Expensive Because of Its Excess?
- When Should You Change Your Motor Insurance Excess?
- Why Can Lower Motor Cover Create Higher Costs After a Claim?
- When Is Responsibility Assessed During a Motor Insurance Claim?
- How Can You Control Monthly Motor Insurance Costs Without Cutting Essential Cover?
Why Does Increasing Your Insurance Excess Often Reduce the Premium?
Increasing your voluntary insurance excess often reduces your premium because you agree to pay a larger share of eligible claim costs yourself. The insurer therefore takes on less financial exposure. However, the premium reduction is not fixed or guaranteed: it depends on the provider’s pricing, your risk profile and the excess options available.
Insurance pricing reflects the expected cost of claims, administrative expenses and other underwriting considerations. By increasing the amount deducted from an eligible claim, you reduce the portion the insurer may need to fund. This can justify a lower premium, but the insurer does not simply return the extra excess to you as a discount.
For example, consider two hypothetical annual quotations for otherwise identical cover:
| Cost component | Lower excess | Higher excess |
|---|---|---|
| Compulsory excess | £200 | £200 |
| Voluntary excess | £100 | £400 |
| Total excess | £300 | £600 |
| Annual premium | £720 | £660 |
| Annual premium saving | — | £60 |
In this hypothetical comparison, the driver accepts an additional £300 of potential excess exposure to save £60 annually. One claim attracting the full difference would offset five years of premium savings, before considering price changes or other claim consequences.
This is consistent with MoneyHelper‘s explanation of insurance excess, which describes how voluntary excess is added to compulsory excess and why affordability matters when deciding whether to increase it.
Insurers may price smaller claims differently from larger losses, and their approaches vary by vehicle, driver and cover. It is therefore unsafe to assume that an excess increase will deliver the same percentage discount at every company.
Higher excess options can also produce progressively smaller savings. This is a possibility to test through actual quotations, rather than an established universal pricing rule. Insurers may limit the voluntary excess you can select.
Request quotes at three available excess levels, holding every other policy detail constant. Compare the additional excess with each incremental premium reduction, not merely the difference between the cheapest and most expensive options.
The most attractive balance is not necessarily the highest excess available. It is the level at which the premium saving remains useful without creating a claim payment you would struggle to fund.
How Can You Set an Excess That Your Emergency Fund Can Actually Cover?
Set your motor insurance excess below the amount of accessible savings you could comfortably use shortly after an incident. Calculate the combined compulsory and voluntary excess, then subtract money needed for essential bills and other foreseeable emergencies. If paying the excess would force you into debt or leave you financially exposed, choose a lower amount.
The distinction between having enough money and being able to afford a claim matters. A bank balance of £1,500 does not necessarily make a £1,000 excess affordable if most of that balance is needed for rent, food or upcoming payments.
A practical calculation is:
Maximum affordable excess = accessible emergency savings − protected emergency reserve.
For example, suppose you have £2,000 available in savings but need to preserve £1,200 for other essential contingencies. Your available excess budget would be £800. This is an illustrative personal budgeting method, not an official insurance-industry threshold.
If the policy has a £250 compulsory excess, a £400 voluntary excess produces a total of £650, leaving £150 within that hypothetical excess budget. A £700 voluntary excess would produce £950, exceeding it.
Timing is another consideration. Depending on the insurer and repair arrangement, you may need to contribute your excess before repairs are completed or the vehicle is released. In other cases, it is deducted from a settlement. You should not assume you can wait for an eventual reimbursement before finding the money.
Credit cards and overdrafts are unreliable substitutes for an emergency fund. Interest and fees could exceed the premium savings you hoped to achieve, particularly if repayment takes several months.
If you currently have no accessible emergency savings, consider selecting a lower voluntary excess, accumulating a dedicated reserve before renewal, or asking whether your insurer offers any flexibility over payment. Instalment arrangements should never be assumed to exist.
Five checks before committing to an excess
- Find your compulsory excess: record the amount from the quotation or policy schedule.
- Add your proposed voluntary excess: write down the combined claim exposure, including any applicable additional excess.
- Calculate available emergency savings: produce a balance that excludes protected essential funds.
- Check the payment arrangements: obtain confirmation of when and how the excess would be collected or deducted.
- Document your affordability decision: keep a comparison showing the total excess, annual premium and remaining emergency reserve.
An affordable excess preserves enough financial flexibility to deal with the accident and whatever other unexpected expenses might follow it. The next step is to confirm exactly which parts of the excess you can control.
Compulsory or Voluntary Excess: Which One Determines What You Pay?
Both compulsory and voluntary excess determine what you pay after an eligible motor insurance claim. The insurer sets the compulsory amount, while you select the additional voluntary amount from the options offered. These amounts are normally combined, so choosing a £400 voluntary excess on top of a £250 compulsory excess creates a £650 total.
The compulsory excess reflects the insurer’s underwriting rules and may vary according to factors such as the driver’s age, vehicle characteristics or claims history. Some policies also specify additional or separate excesses for particular drivers, losses or types of claim.
The voluntary excess is the component you usually have greater control over. Increasing it may lower the premium, whereas reducing it can increase the premium. Neither decision changes the compulsory amount unless the insurer separately changes its terms.
Consider a hypothetical accepted repair claim of £2,500 with a £650 total excess. If the full excess applies, £1,850 remains payable by the insurer towards eligible repairs, subject to the policy’s other conditions.
Comparison websites can make this distinction easy to overlook when customers focus primarily on monthly premiums. The necessary breakdown may appear within quote details rather than alongside the headline price. This does not mean all comparison services conceal it.
Before buying, inspect the policy schedule and quotation summary for:
- The standard compulsory excess and any driver-specific additional excess.
- The voluntary excess you selected and whether it applies to the relevant claim.
- Separate arrangements for windscreen damage, theft or other specified incidents.
- Any restrictions or special conditions affecting particular drivers.
A young driver, for example, may face a substantial insurer-imposed excess and therefore have relatively little financial room to add a voluntary amount. Their quote comparison should prioritise the total payable amount rather than the voluntary figure alone.
It is also useful to calculate an indicative first-year cost under two scenarios: no claim and one eligible claim attracting the full stated excess. That provides a clearer comparison than the premium by itself, although it is not an estimate of how likely a claim is.
Knowing the breakdown makes policy comparisons more meaningful and prevents a cheap-looking quotation from disguising a larger financial commitment.
How Can a Cheap Policy Become Expensive Because of Its Excess?
A cheap motor insurance policy can become expensive when its high excess outweighs the premium savings after a claim. The comparison is straightforward: calculate the annual saving, identify the additional excess you would pay, and divide that additional exposure by the annual saving. The result shows how many claim-free years would be needed to offset that extra cost.
Consider two hypothetical comprehensive insurance quotations offering equivalent cover:
| Cost | Policy A | Policy B |
|---|---|---|
| Annual premium | £720 | £540 |
| Total excess | £300 | £900 |
| One-year premium plus full excess | £1,020 | £1,440 |
| Annual premium saving with B | — | £180 |
Policy B saves £180 in a claim-free year but exposes the driver to an additional £600 if a claim attracts the full excess difference.
The simple break-even calculation is £600 ÷ £180 = approximately 3.33 years. In this static example, four full claim-free policy years would generate £720 in cumulative premium savings, exceeding the £600 extra excess. This calculation assumes unchanged premiums and one comparable claim; it is not a prediction of future costs.
Smaller losses make the high-excess problem more visible. If eligible repairs cost £700 but the applicable excess is £900, the policy would ordinarily provide no payment towards those repairs. The driver would effectively fund the work themselves.
Even where claiming is possible, future premium changes or no-claims discount consequences may influence the decision. Reporting an incident and making a claim are not always the same thing. Drivers should follow their policy’s notification obligations even when they intend to pay for repairs privately.
The same affordability issue can arise after a non-fault accident. Your insurer might initially apply the excess while seeking payment from the responsible party. Reimbursement is not necessarily immediate, and recovery may be complicated if the other driver is uninsured or cannot be identified.
According to MoneyHelper’s car insurance claims guidance, excess is ordinarily deducted from accepted claim settlements, and a written-off vehicle is typically valued at its current market value before applicable deductions.
Hypothetical example: a high excess on an older car
A driver insures a vehicle worth £1,800 with a £1,000 applicable total excess. If an insured incident results in a total-loss valuation of £1,800 and no other adjustments apply, the illustrative settlement would be £800.
The driver must therefore consider whether the premium paid for comprehensive protection provides enough useful financial benefit relative to the car’s value. Cover for liability to others and other insured events must still be considered separately.
A useful comparison also looks at claims handling. Check how repairs are authorised, whether the excess is payable directly to a repairer, and how the insurer handles recovery from another party. A low headline price is less attractive when claim procedures create avoidable financial pressure.
The decision also depends on what the policy covers. A low premium paired with high excess and substantial exclusions can expose you to several different costs from a single incident.
When Should You Change Your Motor Insurance Excess?
Review your motor insurance excess whenever your financial reserves, vehicle value or driving circumstances change significantly. Renewal is usually the simplest time to compare excess options, although some insurers may permit changes during a policy term. The aim is to keep your potential claim payment affordable, not to increase the excess automatically each year.
A driver who builds a larger emergency fund may be able to accept a higher voluntary excess. Conversely, someone who has used savings for a major expense may benefit from lowering it, even if the annual premium increases.
Vehicle changes matter too. Replacing an older car with a more valuable one can alter the financial consequences of a claim. Equally, a car that has depreciated substantially may justify a review of the relationship between the total excess, vehicle value and premium.
Other circumstances worth reviewing include:
- A significant change in household savings or essential expenditure.
- Buying or replacing a vehicle.
- Moving home or changing regular parking arrangements.
- Adding or removing a driver.
- A change in driving patterns or annual mileage.
- A new claim or a period of claim-free driving that changes available quotations.
At renewal, request revised quotations using the same cover with different voluntary excess amounts. Compare the full annual premiums rather than only the monthly instalments.
Mid-term adjustments may be possible, but availability depends on the insurer’s rules. A change could lead to repricing, an administrative charge or revised terms. Ask whether an adjustment affects any existing promotional price before agreeing to it; a universal penalty or cancellation of discounts should not be assumed.
Lowering the total excess from £800 to £400 might, hypothetically, add £90 to the annual premium. The driver would be spending £90 a year to reduce the applicable excess exposure by £400. Whether that is worthwhile depends on their liquidity, risk tolerance and the likelihood of making relevant claims.
After a claim, check whether the excess remains suitable for your remaining savings. However, do not assume an amendment to your current policy can retrospectively alter an excess that applied when an incident occurred.
Excess adjustments are most useful when considered alongside the broader protection the policy provides. Changing the deductible cannot compensate for essential cover that is missing.
Why Can Lower Motor Cover Create Higher Costs After a Claim?
Reducing motor insurance cover can increase post-claim costs because the insurer may no longer pay for losses that a broader policy would have covered. When restricted protection is combined with a high excess, the driver can face both the applicable claim contribution and separate uninsured expenses. A lower premium therefore does not necessarily mean a lower total financial risk.
The distinction between insurance excess and exclusions is fundamental. An excess is your contribution to an otherwise eligible claim. An excluded loss, by contrast, may receive no payment under that policy at all.
For example, a driver involved in an accident could face a £600 excess on insured vehicle repairs while also paying separately for temporary transport if a courtesy vehicle is not provided. The exact expenses depend on policy terms and circumstances.
UK motor insurance commonly distinguishes between third-party cover, third-party fire and theft, and comprehensive cover. These categories provide different levels of protection for damage to the insured driver’s own vehicle.
As explained in MoneyHelper’s car insurance guidance, comprehensive insurance is not necessarily more expensive than third-party-only cover. The price should therefore be tested with actual quotations rather than inferred from the name of the cover level.
Consider what a realistic accident could require you to pay:
| Expense | Question to check |
|---|---|
| Repair excess | What total excess applies to this particular claim? |
| Replacement transport | Is a courtesy car provided, and for how long? |
| Windscreen damage | Is glass covered, and does a different excess apply? |
| Recovery or breakdown | Are towing and recovery costs covered in the relevant circumstances? |
| Legal expenses | What legal assistance is included, and what limits apply? |
| Excluded vehicle damage | Would the selected cover pay for damage to your own car? |
These costs should not all be treated as automatic consequences of an accident. They are possible financial exposures whose relevance varies by claim and policy.
A particularly important issue arises when the excess represents a large share of the vehicle’s market value. Comprehensive insurance may still protect against substantial covered losses, but its practical payout on certain claims could become relatively small.
Equally, comprehensive cover does not make every repair or expense eligible. Policy limits, exclusions and separate excess terms remain important.
The appropriate policy protects against losses you could not comfortably absorb, while avoiding duplicate or unnecessary extras. Understanding how responsibility is assessed after an accident adds another dimension to that decision.
When Is Responsibility Assessed During a Motor Insurance Claim?
Responsibility is assessed as an insurer investigates the circumstances of a motor accident, rather than necessarily being established when the incident is first reported. The insurer reviews available evidence, considers the accounts of those involved and determines how the claim should be handled. The resulting liability and cost-recovery decisions may affect your excess and no-claims record.
Immediately after an incident, the insurer will normally need details about the vehicles, drivers, damage and events. Photographs, witness information and other contemporaneous records can help establish what occurred.
Where available and legally obtained, relevant evidence may include dashcam footage, CCTV, repair assessments and police documentation. No single item automatically determines responsibility in every case.
Once sufficient information has been reviewed, insurers may agree liability, dispute it or consider shared responsibility. The claim can remain unresolved while further evidence is obtained or another insurer’s position is established.
The distinction between causing an accident and having a fault claim recorded is especially important in UK insurance.
The Financial Ombudsman Service‘s explanation of fault claims confirms that an insurer may classify a claim as fault when it cannot recover its costs from another party, even where its customer did not personally cause the accident.
For example, damage caused by an unidentified driver to a parked vehicle can create an unrecovered insurance claim. The classification may affect an unprotected no-claims bonus, depending on the relevant arrangements.
If the other party accepts liability and their insurer pays the relevant costs, a previously applied excess may be recoverable. However, recovery procedures and timescales depend on the jurisdiction, claim route and insurers involved.
Shared-liability cases require particular care. An insurer may agree an allocation of responsibility that influences recovery, but there is no universal formula in the supplied UK guidance establishing precisely what proportion of excess is refunded in every split-liability case.
Drivers should ask their insurer how the proposed settlement affects the excess, what amounts remain recoverable and whether the no-claims record can be revised after recovery.
Keeping an organised record of the claim is useful: save photographs, contact details, repair estimates, correspondence and confirmation of decisions. Clear records can reduce confusion if the insurer later requests supporting information.
Because reimbursement may be delayed or uncertain, the original excess should still be affordable even in a situation where you believe another driver caused the accident.
Key takeaways before choosing your next policy
- Lower premiums are most valuable when they preserve protection against major expenses you cannot comfortably fund yourself.
- Use annualised quotations with identical cover to distinguish real savings from additional risks or payment charges.
- Check your circumstances and policy information carefully; inaccurate declarations can undermine the protection you are paying for.
How Can You Control Monthly Motor Insurance Costs Without Cutting Essential Cover?
You can often manage motor insurance costs without increasing your claim exposure by comparing equivalent policies, reviewing payment arrangements and ensuring your declared driving circumstances are accurate. Paying annually may reduce instalment-related charges, while checking duplicate add-ons and obtaining renewal quotations can identify savings without weakening essential protection.
Monthly payment amounts require particular attention. Where an insurer charges interest or fees for instalments, twelve monthly payments can exceed the price of paying the annual premium upfront. Compare the total payable rather than the monthly figure alone.
Paying annually is only sensible if doing so does not undermine the savings you need for other essentials. Using expensive borrowing to fund an annual payment may eliminate the apparent benefit.
Accurate annual mileage is another important pricing consideration. A lower genuine mileage estimate may produce a different quotation, but deliberately understating how much you drive is not a legitimate saving strategy. Incorrect information can create claim or coverage difficulties depending on its significance and the policy’s terms.
The same principle applies to vehicle modifications, regular drivers, parking arrangements and declared use. Provide correct information and ask the insurer whether a material change affects the price or terms.
Other opportunities include checking whether roadside assistance already comes with your vehicle or another membership, whether optional cover is duplicated, and whether a different insurer offers equivalent protection for less.
At renewal, a practical comparison should use the following sequence:
- Write down your current annual premium, total excess and essential cover benefits.
- Obtain alternative quotations with equivalent limits, drivers and declared circumstances.
- Compare annual payment totals and any monthly instalment charges.
- Request different available excess options without changing other policy features.
- Confirm exclusions, claims procedures and optional benefits before selecting a policy.
Increasing the voluntary excess remains an available strategy, but it is fundamentally different from finding a lower price for equivalent protection. The former transfers additional financial risk to you; the latter may reduce expenditure without increasing the amount you bear after a covered claim.
There is also no reason to assume that remaining with the same insurer always offers the best price. Comparing renewal quotations can reveal whether a competitive offer exists for the cover you actually require.
For your next renewal, collect three like-for-like quotations at different excess levels, calculate the annual savings and identify the maximum claim contribution you could pay promptly. Select the option that preserves essential cover while keeping a possible claim financially manageable.
Do you pay the insurance excess if your car is written off?
Where the applicable excess applies to an accepted total-loss claim, the insurer typically deducts it from the vehicle’s assessed market value, subject to the policy terms and other adjustments. For example, an illustrative £4,000 valuation with a £500 applicable excess would produce a £3,500 settlement before any other deductions or payments.
Can you pay your car insurance excess in instalments?
Payment arrangements depend on the insurer, claim process and repairer. Some may offer flexibility, but there is no general guarantee that the excess can be spread over instalments. Ask about payment terms before choosing an excess you could not otherwise pay promptly.
Is motor insurance excess payable on every claim?
Not necessarily. The applicable excess can differ by claim type, and some policy benefits have separate terms or excess arrangements. Windscreen claims, for example, may be treated differently from accidental vehicle damage. The policy schedule and wording determine which excess applies.
Does a protected no-claims bonus prevent premium increases after an accident?
No. No-claims bonus protection may preserve a particular discount under the policy’s rules, but it does not guarantee an unchanged premium. Insurers can still reprice cover based on claims experience and other underwriting factors. Check both the discount protection conditions and the full renewal price.
Is a high voluntary excess worth choosing if you rarely claim?
It may be worthwhile if the premium reduction is meaningful and you have sufficient accessible savings to cover the full applicable excess. However, rarely claiming does not eliminate the possibility of a costly incident. Compare the premium saving with the additional excess and consider how much financial disruption an unexpected claim could cause.